-
Shop
- Advanced Technologies
- AI Skills
- Bathroom
- Best-Sellers
- Car Accessories
- Confidence
- Dating & Social Skills
- Digital Resources
- AI & Technology
- Beauty
- Budgeting & Saving
- Car Buying & Ownership
- Cozy Feast Collection
- Electronics & Technology
- Entrepreneurship & Business Growth
- Financial Education
- Financial Independence
- Financial Mindset & Psychology
- Goal Setting
- Home Styling & Organization
- Kitchen & Recipes
- Leadership
- Mindfulness
- Mindset
- Online Business
- Parenting & Child Development
- Personal Style & Fashion
- Pet Lifestyle & Wellness
- Positive Thinking
- Sleep Improvement
- Smart Life with AI
- Stress Management & Relaxation
- Travel Planning
- Wellness
- Yoga & Fitness
- Yoga & Mind-Body Practices
- Education & Learning
- Family & Parenting
- Fashion
- Accessories
- Alexander McQueen
- Bags
- Bags & Wallets
- Balenciaga
- Belts
- Blazers
- Bottega Veneta
- Bottoms
- Brunello Cucinelli
- Burberry
- Chanel
- Chloé
- Dior
- Dolce & Gabbana
- Dresses
- Etro
- Fendi
- Gucci
- Hats & Hair Accessories
- Hoodies & Sweatshirts
- Jacquemus
- Jewelry
- Jil Sander
- Kiton
- Luggage
- Miu Miu
- Off-White
- Outerwear
- Prada
- Rick Owens
- Saint Laurent
- Shoes
- Socks & Tights
- Sweaters & Cardigans
- The Row
- Tom Ford
- Tops & Shirts
- Valentino
- Valentino Garavani
- Versace
- Vivienne Westwood
- Watches
- Fashion Accessories
- Furniture
- Gadgets
- Health & Beauty
- Health & Wellness
- Home & Garden
- Home Decor
- Home Electronics
- Home Supplies
- Kids & Babies
- Kitchen
- Kitchen Best-Sellers
- Lighting
- Patio, Lawn & Garden
- Personal Growth
- Pet Care
- Pet Supplies
- Pets
- Sport & Outdoors
- Super Deals
- Travel
- Travel & Adventure
- Wealth
- Popular
- Best deals
Your Ultimate Retirement Planning Checklist: Get Ready
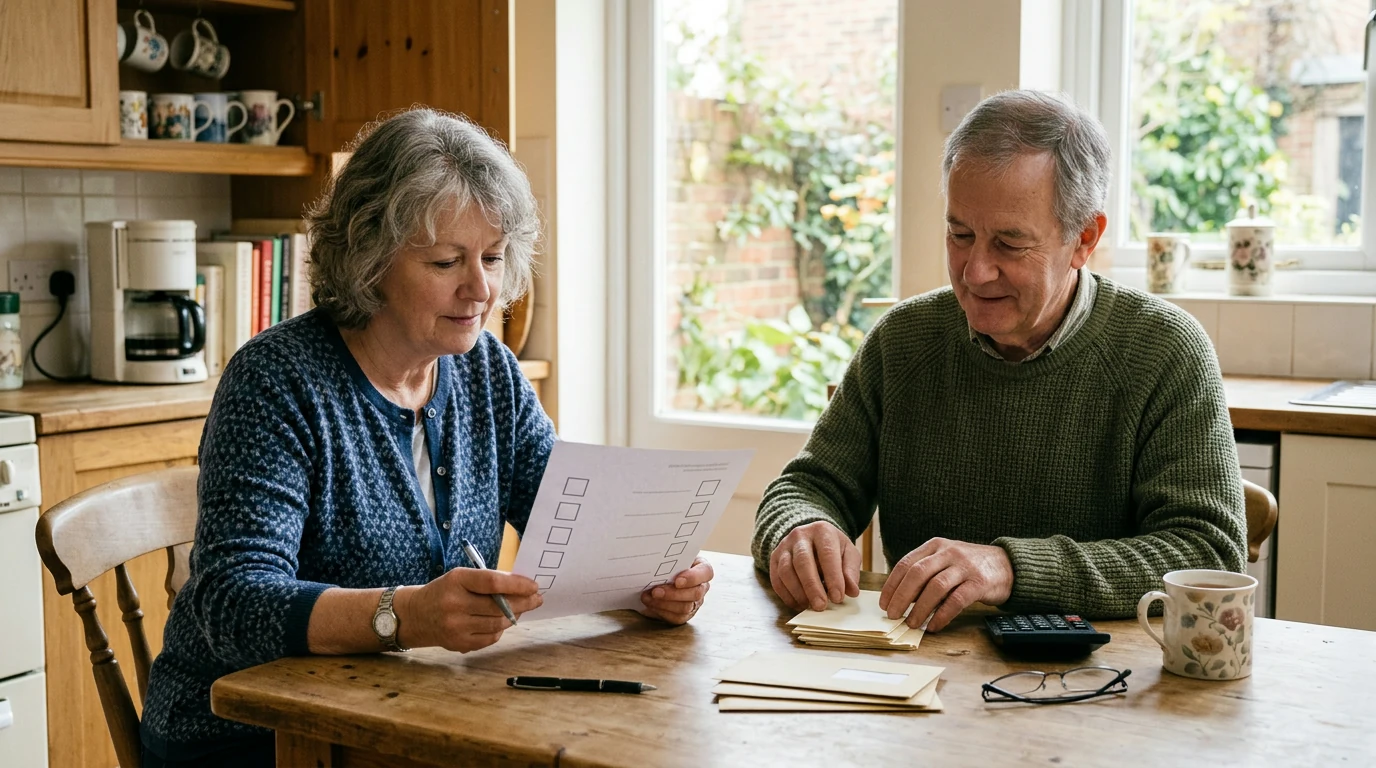
Retirement planning can feel like a collection of big decisions that all need answers at once. Breaking those decisions into smaller tasks makes it easier to see what you know, what you still need to gather, and where you may want professional guidance.
Our Your Ultimate Retirement Planning Checklist offers a practical way to organize those tasks, from estimating expenses to reviewing income and healthcare needs. You can start with a rough picture and refine it as your priorities and circumstances change.
Start with your retirement picture
Before working through numbers, consider what you want retirement to look like. When do you hope to leave full-time work? Do you expect to stay in your current home, move closer to family, or relocate? You might also want to travel, volunteer, work part-time, or spend more time on hobbies.
These choices affect your budget. For example, moving could change your housing costs and taxes, while continued work could affect both your income and your schedule. You do not need a perfect answer today; a working set of assumptions gives you a place to begin.
Separate essential expenses, such as housing and food, from flexible goals, such as travel or entertainment. That distinction can help you identify which costs need dependable funding and which plans you could adjust if needed.
Take stock of income, savings, and expenses
Gather recent statements for retirement accounts, bank accounts, investments, and debts. Then list the income you expect from sources such as Social Security, a pension, part-time work, or other assets. The Social Security Administration’s retirement resources can help you explore benefits and estimates.
Next, draft a monthly retirement budget. Include housing, utilities, food, transportation, insurance, debt payments, taxes, and everyday spending. Allow for inflation and irregular expenses, such as home repairs or replacing a vehicle. Compare the total with your expected income to identify any gap that savings may need to cover.
The table below is a starting point for organizing information, not a complete financial plan.
Retirement planning starting points
| Planning area | Information to gather | Next step |
|---|---|---|
| Income | Estimated Social Security, pension, and other income | Compare expected income with expenses |
| Savings | Retirement and other account balances | Review contributions and withdrawal needs |
| Expenses | Housing, food, transportation, and debt costs | Draft a monthly retirement budget |
| Healthcare | Coverage options and expected costs | Review eligibility and potential gaps |
If your first budget shows a shortfall, use it as a prompt for further decisions rather than a final verdict. You might revisit your retirement date, savings rate, spending goals, or expected work income. A financial professional can help you evaluate the tradeoffs for your situation.
Make room for healthcare and the unexpected
Healthcare deserves its own line in your plan. Explore Medicare eligibility and enrollment timing, and consider how you would obtain coverage if you retire before you are eligible. The official Medicare getting-started guide explains the basics and can help you find enrollment information.
Look beyond premiums, too. Consider deductibles, prescriptions, dental care, vision care, and other potential out-of-pocket expenses. Your needs and coverage choices may change over time, so revisit these estimates regularly.
Unexpected costs can also disrupt a carefully drafted budget. Consider how much you want to keep in emergency savings and review your insurance coverage. Potential long-term care costs are another topic to discuss with a qualified professional, especially when deciding how much flexibility your plan needs.
Put the checklist to work
Set aside a dedicated planning session and bring together your statements, benefit estimates, debt information, and a draft budget. Work through one area at a time, noting what is complete and what needs follow-up. If you share financial decisions with a spouse or partner, make time to compare your priorities and assumptions.
Our Your Ultimate Retirement Planning Checklist is available for $5.99. It can help you approach retirement tasks in an organized way and keep track of questions to raise with a financial or tax professional.
For example, you might ask how withdrawals could affect your taxes, whether your debt repayment schedule fits your retirement date, or how to prepare for a gap in healthcare coverage. Write down the answers and the next actions you agree to take.
If running a business is part of your longer-term plans, we also offer the AI for Small Business Toolkit – 5-in-1 Digital Download Bundle. Keep any business spending and potential income separate in your retirement budget so you can assess those assumptions clearly.
Keep your plan current
Review your plan at least once a year and after a significant change in income, health, family circumstances, or retirement timing. Update account balances, expense estimates, and benefit information, then check whether your priorities still fit your resources.
A checklist helps you stay organized, but it does not replace personalized financial, tax, or legal advice. Our team recommends bringing your questions to qualified professionals who can address your individual circumstances.
FAQ
When should I start planning for retirement?
Start as early as practical, but reviewing your income, expenses, and goals can be useful at any stage. Even if retirement is close, identifying gaps and priorities can help you decide what to address next.
What should I review in a retirement plan?
Review your expected income, savings, expenses, healthcare coverage, debt, and emergency reserves. Revisit your assumptions as your circumstances change.
Can a retirement checklist replace financial advice?
No. A checklist can organize tasks and questions, while a qualified professional can provide advice suited to your individual circumstances.
Recommended for you

Sweet Zircon Bee Stud Earrings: Styling and Care
Nov 19, 2026



Leave a comment